Core research topic
Petroleum and Natural Gas
Upstream hydrocarbon research, production, and markets.
China Energy Demand
This briefing tracks China's energy demand and import strategy, covering its rise to the world's largest LNG importer in 2021, continued reliance on coal, evolving gas and pipeline infrastructure incentives, and its pursuit of supply diversity amid shifting geopolitical alignments.
11 publications
Crude Exports and Petroleum Infrastructure
Since the U.S. crude export ban was lifted in December 2015, exports have grown to over 4 million barrels per day, with roughly 1.4 million flowing to Europe, though limited planned pipeline capacity through 2030 could constrain further growth.
29 publications
Deepwater Gulf of Mexico and Offshore Governance
The Gulf of Mexico is a major U.S. offshore oil and gas province spanning federal, state, and Mexican waters, where deepwater exploration and post-Macondo regulatory decisions on drilling moratoria carry significant consequences for domestic production and energy security.
9 publications
European Gas Security and Russian Supply
Since mid-2022, U.S. LNG has displaced collapsed Russian pipeline gas in Europe, with U.S. LNG exports rising to 11.7 BCF/d and the European share climbing to 81%; the January 2025 expiry of Ukrainian transit removed a further 1.5 BCF/d, leaving European inventories below trend.
50 publications
Iraq and Middle East Oil Supply
This briefing covers Iraqi and broader Middle East oil supply, including sanctions on Iranian exports of roughly 1.5 million barrels per day, OPEC+ production management, and the security of tanker traffic through the Red Sea and Strait of Hormuz amid regional military conflict.
8 publications
Keystone XL and Canadian Oil Sands
Canada supplies roughly 2.8 million barrels per day of crude to U.S. refineries, nearly all its exports; this briefing covers the oil sands, Keystone XL pipeline access to Gulf Coast refineries, and the cost impact of U.S. tariffs on Canadian crude.
21 publications
Mexico Oil and Gas
Mexico is an integral part of the North American petroleum platform, supplying 780,000 barrels per day of crude to U.S. refineries, while its own oil reserves and PEMEX-led production face structural decline and policy-driven constraints.
24 publications
Net Zero and the Energy Transition
This briefing examines the feasibility and pace of net-zero pathways, comparing projected U.S. emissions contributions from new gas-fired plants and vehicles against global totals, and assessing grid reliability, electrification costs, and hydrocarbons' persistent role in global power generation.
45 publications
North American Shale and Tight Oil
Shale and tight oil have made the United States the world's largest oil and gas producer, with per-well productivity rising sharply even as rig counts and operational leases decline, though producer breakeven WTI costs have climbed from roughly $29 to $39/bbl since 2020.
61 publications
Oil and Gas Taxation and Regulatory Reform
This briefing covers federal oil and gas leasing, royalty, and taxation policy, including onshore versus offshore royalty trends and foregone tax revenues projected at $57.4 billion through 2024.
22 publications
Oil Production Outlook and Peak Oil Debate
This briefing examines U.S. and global oil production trajectories and the recurring peak oil debate, including shale efficiency gains that tripled Lower 48 output on 25% fewer federal leases since 2015, upstream underinvestment, and diverging long-term demand forecasts.
24 publications
OPEC and Global Oil Markets
This briefing tracks OPEC and OPEC+ production management, sanctions on Iranian and Russian crude, and Middle East conflict risk to tanker traffic, alongside U.S. production dynamics: the interacting forces that set global crude prices and benchmark discounts.
27 publications
Russia-Ukraine Energy Disruption
The war has severed Russian energy flows to Europe: pipeline gas fell from a 2019 peak of 15 BCF/d to under 1 BCF/d, Ukraine ended Russian transit on January 1, 2025, and sanctions plus Ukrainian refinery strikes have reshaped Russian crude and product exports.
26 publications
Strait of Hormuz and Oil Chokepoints
The crisis escalated again through late summer. Iran ruled out talks to extend the June 17 memorandum of understanding that was meant to open the strait while a nuclear deal was negotiated. After a month-long lull, fighting flared in early September: on September 2 the U.S. struck two Iranian government tankers under a new "tanker for tanker" policy aimed at deterring Iranian attacks on shipping, and by September 9 it had sunk five more near Kharg Island and in the Gulf of Oman, while Iran said it attacked 10 ships near the strait and fired missiles at U.S. forces in Jordan. Traffic remains a fraction of the roughly 130 daily transits before February 28; Windward counted 12 transits on September 22, several with transponders off, and the Joint Maritime Information Center still rates the strait's risk as severe, citing possible drifting mines.
The bypass routes have now come under attack as well. Drones struck Saudi Arabia's East-West Pipeline on September 10, and Riyadh shut the line on September 11, halting loadings at Yanbu. The pipeline had been rerouting about 4 MB/d, roughly 4% of global supply, to the Red Sea. With some European cargoes cancelled, Brent settled at $108.75 on September 15, its highest since May 19, about 54% above its July 2 low of $70.65. The pipeline restarted September 22 and Brent touched $97.36, then settled at $103.08 on September 23 after Iran's president vowed never to surrender. Tehran has signaled it would reopen the strait within seven days if Washington moves toward lifting the blockade, but no framework has been agreed.
The Strategic Petroleum Reserve has continued to fall, though more slowly than projected in July. It held 285.0 million barrels in the week ending September 11, the lowest since November 1982 and 39.9% of authorized capacity. That is 31.5 million barrels below the July 10 level, or about 14 days of U.S. consumption at 20.1 MB/d. The strain has shifted downstream: U.S. diesel is above $6 per gallon, past the June 2022 record, with refiners running at 98% utilization.
34 publications
Strategic Petroleum Reserve
The U.S. Strategic Petroleum Reserve, tapped for a record 220-million-barrel drawdown between November 2021 and March 2023, fell to roughly half of capacity and has since been further depleted following the 2026 Hormuz Strait blockade, constraining emergency import coverage.
19 publications
US LNG Exports and Asian Gas Markets
U.S. LNG export capacity in operation reached 18 BCF/d as of December 2025, with another 15 BCF/d under construction; Asian markets remain exposed to supply disruptions such as a Strait of Hormuz closure, which would remove roughly 10.6 BCF/d of Qatari LNG.
65 publications
US Refining Industry
U.S. Gulf Coast refineries account for 55% of national refining capacity and remain optimized for medium and heavy sour crudes, sustaining reliance on imports from Canada, Mexico, and Venezuela even amid abundant domestic light crude.
31 publications
Venezuela Oil
This briefing examines the U.S. crude oil trade with Venezuela, which fell from 730,000 barrels per day (9.25% of imports) before 2019 sanctions to about 170,000 barrels per day since 2023, and the sector's prospects following the January 2026 removal of Maduro.
7 publications
Latest in this topic
All publications in this topic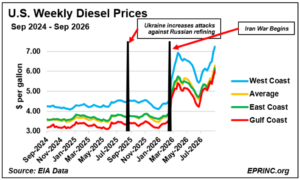 ChartU.S. Diesel Price Spikes and Why an Export Ban Would BackfireWith little letup in hostilities and substantial damage to Persian Gulf and Russian refining capacity, global diesel prices have surged. The U.S.…
 ChartU.S. Crude Oil and Product Export Response to Hormuz Closure: The Rotterdam and Tokyo SurgeU.S. crude oil trade, already narrowing on the back of surging domestic production, tightened further in the second quarter of 2026. Net…
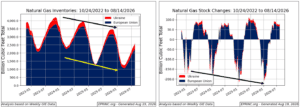 ChartEuropean Natural Gas Inventories: A Record-Low Buffer Entering WinterEurope and Ukraine hold a combined 5 tcf of natural gas storage capacity (4 tcf and 1 tcf, respectively), but this year’s refill has fallen…
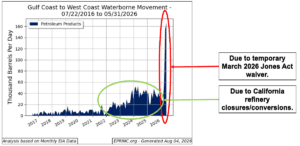 ChartWest Coast Product Receipts: The Jones Act Waiver’s Sixfold SurgeCombined April and May 2026 waterborne receipts of Gulf Coast petroleum products into the U.S. West Coast reached 377 thousand barrels per…
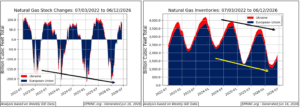 ChartNatural Gas Inventories in the Northern Latitudes: A Mid-Year ReviewRecent harsh winters across the northern latitudes have elevated reliance on natural gas for seasonal power and heating in both the U.S.…SalonPressEPRINC’s Max Pyziur Interviewed by Salon.com About the Current Status of the Hormuz Closure and Its Ramifications on Global Energy Flows and PricesEPRINC’s Max Pyziur was interviewed by Salon.com about the current status of the Hormuz closure and its ramifications on global energy flows…
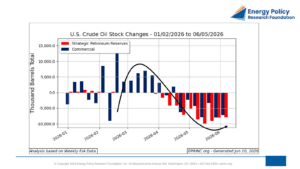 ChartU.S. Crude Inventories, Strategic and Commercial, in the Wake of HormuzFollowing the Hormuz Strait blockade, U.S. crude oil inventories declined from 855 million barrels at the end of February 2026 to 776…
 ReportFYI In Brief: Shifts in U.S. Jet Fuel Prices and Commercial Air TravelThe ongoing war between Israel / U.S. and Iran that has led to a blockade of the Hormuz Strait has led to…